Intelligence · Germany
All the intelligence you need to enter Germany, and to make the most of it once you're in.
The world’s largest regulated medical cannabis market — 205 tonnes imported and a €1bn+ pharmacy market in 2025 — just posted its first import decline on record, and the state has already stripped flower from reimbursement. Cannamonitor tracks every layer of it.
Annual imports, tonnes (BfArM), 2018–2025. Q1 2026 posted the first decline on record — see below.
The snapshot
One market, five signals.
Biggest, fastest-moving and most contested — in five figures. Every one of them is a live, sourced series in Decide, not a static headline.
205 t
imported in 2025
+182% YoY
€1bn+
pharmacy sell-out
2025
~900k
patients
mid-2025
−52%
retail flower
Apr 2024 → Jun 2026
~€205M
reimbursement removed or gated
flower cut Jul 2026 · extracts Jan 2027
Our German coverage
Germany, as we’ve reported it.
Every claim on this page traces back to published analysis. Here is the German file — imports, pricing, reimbursement and the science — in the order it broke.

PricingJul 2026
Germany’s price reset: 52% wiped off pharmacy prices in two years
Read →
ReimbursementJul 2026
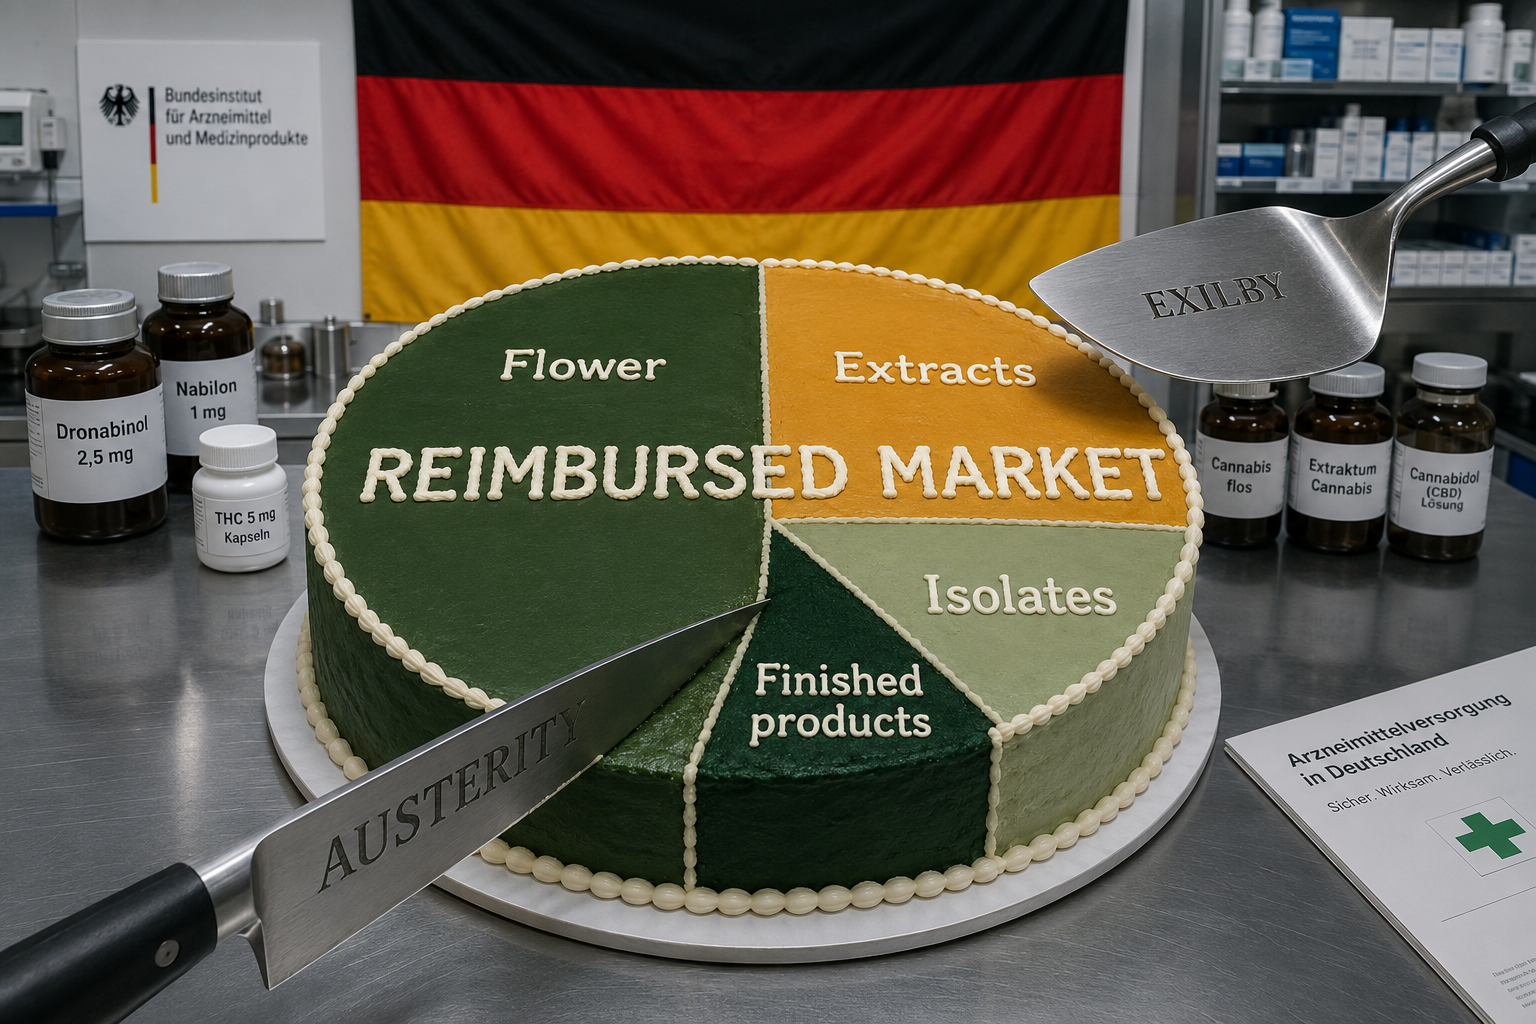
Germany’s six-month gate: 82% of reimbursed cannabis at risk
Read →
ScienceJul 2026
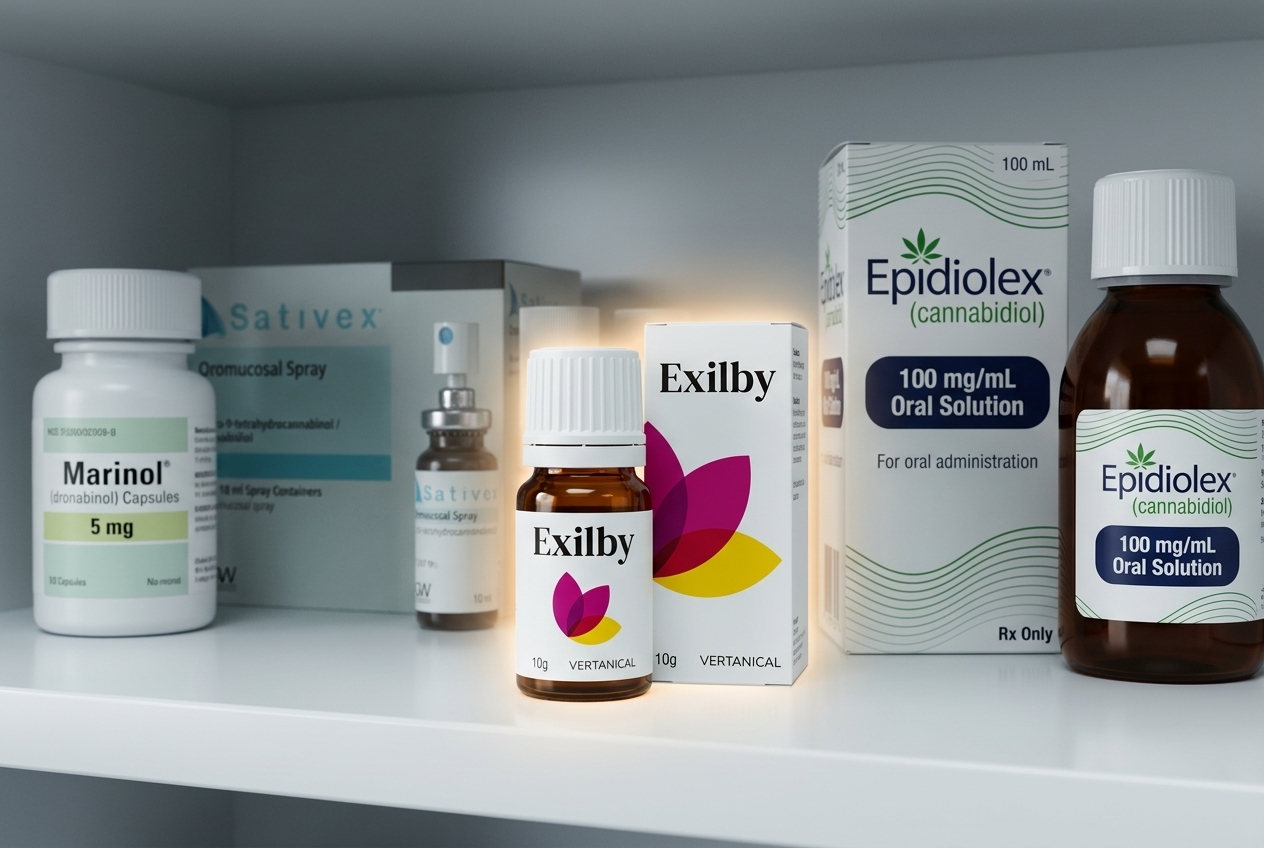
Cannabinoids come of age: the trial pipeline behind Exilby
Read →
SupplyMar 2026
Germany imports 201 tonnes and crosses €1 billion in sales
Read →
TradeSep 2025
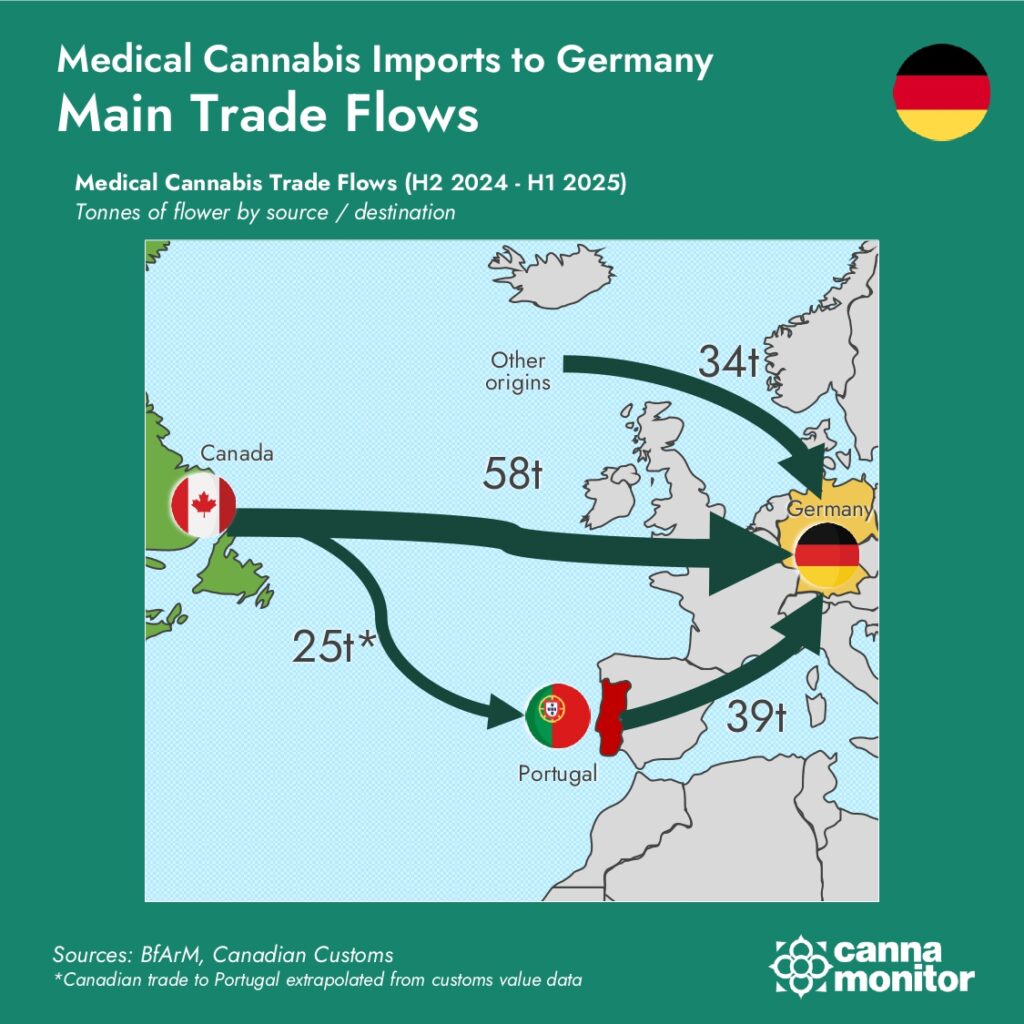
The transatlantic triangle: Canada, Portugal & Germany under pressure
Read →
MarketApr 2025
Germany’s medical cannabis market boom continues in 2025
Read →
Supply
The supply curve just bent.
Imports scaled 32 t (2023) → 73 t (2024) → 205 t (2025), then fell for the first time on record in Q1 2026 — −16.8% QoQ, 60.8 t → 50.5 t. Sequential growth had already been decelerating through 2025 (Q3 +24% → Q4 +3%) before it inverted. Canada (46%) and Portugal (27%) dominate origin; domestic production is under 10 t — Germany imports roughly 30× what it grows.
Imports, quarterly (tonnes)
BfArM quarterly releases, Q1 2024 – Q1 2026 · ~6–8 week reporting lag
Nine quarters on record. Q1 2026 is the first decline — annualised run-rate ~202 t, essentially flat to 2025 and well below the ~230 t pre-Q1 projection.
Origin mix, 2025 (tonnes)
Share of the 205 t imported
Two origins supply nearly three-quarters. Malta +7,611% and the UK +6,090% off tiny bases as firms routed around Iberian bottlenecks.
Supply balance (tonnes)
Imports vs exports vs domestic output
Domestic figure is an INCB pre-estimate. Exports fell 21% — Germany is overwhelmingly a demand market.
→ In Decide the full quarterly import and export series by country of origin, plus the domestic-production pipeline — Germany import, export & production data, refreshed on each BfArM release.
Demand
Demand outran the doctors — so telemedicine took over.
Patients scaled from ~250k at CanG passage (April 2024) to ~900k by mid-2025. Our own projection is 1.2M by 2027 and 1.3M by 2028 — growth continuing, but flattening, and deliberately below the operator forecasts circulating in the market. But only about 1 in 10 GPs will prescribe — zero willingness was recorded in Berlin, Frankfurt and Bielefeld — so telemedicine platforms became the acquisition engine. That channel is now the exact target of the MedCanG amendment.
Patients (thousands)
Actual to mid-2025; 2027–28 are Cannamonitor projections
Projections are our own, shown lighter — deliberately below the operator forecasts circulating in the market.
Telemedicine traffic, Jun 2026
Estimated monthly visits · top 6 of 42 tracked operators
Total ~8.1M visits. Doktor ABC alone is 39% of tracked traffic. Cannamonitor compilation, ±10–15% on smaller sites.
The prescriber bottleneck
~1 in 10
GPs willing to prescribe. Zero willingness recorded in Berlin, Frankfurt and Bielefeld — the structural reason the platform channel exists.
Demand routed through telemedicine
70–80%
Channel mix across tracked traffic: telemedicine 76% · comparators 20% · pharmacies 3% · homegrow 1%.
→ In Decide the patient and prescriber series, and the monthly telemedicine traffic panel — 42 operators, updated monthly, with the cross-country comparison alongside (UK, Poland, Switzerland and more).
Price
Prices are falling faster here than anywhere.
Retail flower roughly halved — Cannamonitor’s reconciled estimate fell €9.65/g (Apr 2024) → €4.65/g (Jun 2026), −52%. Wholesale broke the €2/g line. The upstream customs corridor confirms it: Canada’s declared price into Germany fell 17% to about €1.9/g. Germany and Australia are now the only major markets where wholesale is still deflating — the UK and Switzerland are rising.
Retail flower, €/g
Cannamonitor reconciled estimate
−52% in 26 months. Volume-weighted cross-check: €5.40/g (Cannamedical, Mar 2026, 86k patients).
Wholesale bands, €/g
Flower, by certification tier
The €2/g line is broken. Canada’s customs corridor (~€1.9/g) lands between the two bands — the cross-check.
The last pricing moat
EU-GMP >20% THC
Certification plus potency is the only tier still holding a premium as the commodity band compresses toward cost.
Canada’s corridor price
−17% YoY
CA$2,877/kg ≈ €1.9/g declared into Germany — independent customs confirmation that the compression is real, not a survey artefact.
→ In Decide retail and wholesale pricing, tier by tier, cross-validated against customs data — Germany pricing analysis, benchmarked against every import market.
Reimbursement
The reimbursement cut has already landed.
Germany’s €249M GKV-reimbursed market (2025, +13%) is being dismantled in two steps. Since 30 July 2026 cannabis flower is struck from §31(6) SGB V — pharmacies can no longer bill statutory insurers, there is no transition period, and it applies to ongoing therapies. That is €124.7M, and those patients are already paying out of pocket. From 1 January 2027 the second provision gates standardised extracts, dronabinol and nabilone behind a six-month trial of an approved finished medicine. Together: ~€205M, 82% of the reimbursed market.
| Category | 2025 (€M) | Δ 2020–25 | Bill status |
|---|---|---|---|
| Flower | 124.7 | +74% | Struck |
| Extracts | 50.7 | +469% | Gated |
| Isolates (mostly dronabinol) | 29.3 | −37% | Gated |
| Pharmaceuticals | 44.1 | +15% | Beneficiary |
| Total | 248.8 | +51% | ~€205M (82%) exposed |
Source: GKV-Gamsi statutory reimbursement, 2025. GKV covers ~20% of pharmacy sales — self-pay is not captured here.
GKV reimbursement 2025, €M
Colour encodes status: struck (gold) · gated (teal) · beneficiary (green)
Extracts grew 5.7× since 2020; isolates fell 37%. Source: GKV-Gamsi.
The paradox
€13–19/g vs ~€5/g
The administered flower price held at €13–19/g while the open market fell to about €5/g. The state is cutting a bill it was never paying market rates on.
Two provisions, two dates, two legal statuses.
2017
Cannabis becomes reimbursable
Flower, extracts and isolates enter §31(6) SGB V. The reimbursed market starts from zero.
2020–25
The bill grows 51%
GKV spend reaches €249M — flower +74%, extracts +469%.
10 Jul 2026
The Bundestag votes
Both provisions pass in one bill: flower struck outright, extracts gated.
In force
30 Jul 2026
Provision 1 — flower cut, in force
Cannabis flower struck from §31(6) SGB V. Pharmacies can no longer bill statutory insurers for flower — no transition period, and it applies to ongoing therapies. €124.7M. Patients are already paying out of pocket.
Enacted, not yet in force
1 Jan 2027
Provision 2 — the six-month gate
Standardised extracts, dronabinol and nabilone stay reimbursable, but only after a six-month trial of an approved finished medicine (Sativex, Canemes, Epidyolex, Exilby). Enacted, not yet in force.
APOTHEKE ADHOC, 31 Jul 2026: since 30 July 2026 pharmacies can no longer bill medicinal cannabis prescriptions to statutory insurers. BKK Dachverband: the new legal situation applies from entry into force, and also to ongoing therapies. DAZ, 23 Jul 2026: ~€130M of savings projected from excluding flower in 2027.
The call
Cannamonitor flagged the finished-medicine displacement three weeks before the amendment surfaced.
Exilby’s June authorisation created the “approved alternative” the gate needs. We wrote that the pivot was coming; on 10 July the Bundestag voted it. Read the GKV reform deep-dive.
→ In Decide the GKV reimbursement dataset, category by category — the GKV reform deep-dive, with every provision dated and traced to source.
Regulation
Reimbursement is one story of fourteen.
The cut did not arrive on its own. Our regulatory tracker holds 14 master stories on Germany across nine subjects, each scored for momentum and risk and tied to the institutions moving it. The pattern it exposes is the useful part: A CDU/CSU-led tightening push, stalled at federal legislative level by SPD refusal — but advancing anyway through the courts, state-level enforcement and independent regulator action. The direction of travel does not show up in the statute book.
14
master stories
9
regulatory subjects
14
regulators tracked
4
licences compiled
01What moves
Every regulatory subject we hold a master story on, with its direction of travel and where it sits in the process.
8 restrictive2 liberalising2 unclear1 neutralReimbursementImplemented
Novel cannabinoids (HHC/THCP)Under review
Prescription rules & telemedicineUnder review
Medical accessUnder review
Adult-use pilot (Pillar 2)Implemented
Pharmacies & dispensationImplemented
Import / exportApproved
Cannabis clubs (CSCs)Implemented
CBD (medicinal & food)Implemented
Adult-use legalisation (CanG)Implemented
LicensingImplemented
Supply-side rules (import & GMP)Implemented
Industrial hempUnder review
Home cultivationImplemented
02How hard, and which way
Each story carries a momentum score from −100 to +100 and a separate risk score. Reimbursement is the most negative on the board.
−100 restrictiveliberalising +100
Reimbursement−90
risk 85/100restrictive
Novel cannabinoids (HHC/THCP)−80
risk 90/100restrictive
Prescription rules & telemedicine−75
risk 72/100restrictive
Medical access−50
risk 80/100restrictive
Supply-side rules (import & GMP)+60
risk 55/100unclear
Industrial hemp+40
risk 55/100liberalising
Home cultivation+80
risk 10/100liberalising
03Who moves it
The institutions actually driving each story — and the licences and authorisations compiled underneath them.
BMG10
BfArM6
Bundestag Health Cttee6
BGH5
G-BA4
Bundestag (plenary)3
BfR2
BLE2
EFSA2
ECHA2
Also tracked: Bundesrat · BMEL · ANSES (FR) · UN CND
Licences compiled
Anbauvereinigung (CSC) cultivation licenceBMGActive
Medical cannabis cultivation licence (BfArM tender)BfArM · BMGActive
Per-cultivar irradiation / processing approvalBfArM · BMGActive
Pillar 2 adult-use model project authorisationBLEDiscontinued
What the board says right now: medical-access tightening is the dominant story — reimbursement (−90), novel cannabinoids (−80) and prescription rules (−75) all carry strong-negative momentum. Adult-use is stable but under indirect pressure. Two liberalising pockets persist: home cultivation (+80, risk 10) and industrial hemp, where the Rauschklausel is collapsing through the courts before any legislative reform arrives.
→ In Decide the live regulatory tracker — 14 German master stories, momentum and risk scored, every regulator, licence and dated signal underneath them, and the same structure across 120+ markets.
Operators & deals
Consolidation is following the volume.
The German market runs across four operator layers — domestic producers, telemedicine platforms and pharmacies, distributors, and pharma and device makers. Below is a selected view of each: the operators that shaped the last two years. Distribution is where the consolidation is landing, because that layer controls the EU-GMP chain between an import licence and a filled prescription.
Production
Domestic cultivation and pharmaceutical manufacturing. Under 10 t a year between them.
AuroraiAuroraOne of three licensed domestic producersCanadian producer running a GMP cultivation facility in Bitterfeld-Wolfen (Solar Valley) — one of the original three winners of the German domestic cultivation tender. Launched the affordability-focused ‘Daily Special’ brand (21–23% THC).HQBitterfeld-Wolfen, DE · Edmonton, CAFounded2014RoleGrower · DistributorOne of three domestic cultivation licencesBrands: Daily Special, MedReleafTilray / AphriaiTilray / AphriaGerman cultivation licence plus the CC Pharma networkFormed from the Aphria–Tilray merger; one of three winners of the German cultivation bid. Owns CC Pharma, the sixth-largest medical cannabis distributor in Germany, and runs EU-GMP production in Portugal serving the German market.HQLeamington, CA · Portugal (EU production)Founded2014RoleGrower · Manufacturer · DistributorFirst Canadian LP to import full-spectrum extracts into GermanyBrands: Tilray, Aphria, CC PharmaDemecaniDemecanBerlin-based domestic cultivator and distributorOne of three licensed domestic producers, and the only wholly German-owned one. Operates cultivation and distribution for the medical market; expanding toward a 4 t/yr target.HQBerlin, DEFounded2017RoleGrower · DistributorOne of three domestic cultivation licencesSize: 11–50 employeesBecanexiBecanexBerlin extraction CDMO for pharmaceutical-grade extractsBerlin Cannabis Extraction — a contract development and manufacturing organisation specialising in cannabis extracts as active pharmaceutical ingredients. Partnered with Bedrocan on PIEX concentrates and with Four 20 Pharma on inhalable therapy.HQBerlin, DERoleManufacturer · R&DPioneer in extraction with a Berlin production sitePartners: Bedrocan, Four 20 Pharma
Telemedicine & pharmacies
The acquisition engine — 70–80% of demand routes through here.
Doktor ABCiDoktor ABCGermany’s largest telemedicine platform by trafficThe leading digital prescribing platform for medical cannabis in Germany, and the single biggest node in the acquisition channel that now drives 70–80% of demand.HQGermanyRoleClinic~3.18M monthly visits — 39% of tracked trafficDr AnsayiDr AnsayMajor telemedicine platform, ~1M monthly visitsDigital prescribing platform. Doctors registered in Germany; physicians across the EU act independently under professional regulations.HQGermanyRoleClinic~990k monthly visits (+3.5% MoM)GrünhorniGrünhornMail-order pharmacy — ~20% share, €33M revenueVertically integrated cannabis pharmacy, manufacturer and distributor with automated prescription processing and its own fulfilment line. Owns Canymed.HQGermanyRoleManufacturer · Distributor · Retailer~20% market share (2023) · €33M revenue · 50–60k patientsBrands: Grünhorn, CanymedBloomwelliBloomwellEurope’s largest digital platform by patient numbersFrankfurt-based; runs Germany’s largest digital platform for cannabis prescriptions by patient count, cooperating doctors and partner pharmacies. Profitable since 2024. Publishes the quarterly Cannabis Barometer. Owns Algea Care.HQFrankfurt, DEFounded2020RoleRetailer · Distributor · Manufacturer~$55M revenue (Forbes); profitable since 2024Founders: Niklas Kouparanis, Dr Julian WichmannFlowzziFlowzzTelemedicine platform and price comparatorDigital prescribing platform for medical cannabis in Germany, with a price-and-availability comparison layer that feeds the comparator share of tracked traffic.HQGermanyRoleClinic~610k monthly visits (−13.0% MoM)CanDociCanDocTelemedicine prescribing platformDigital prescribing platform for medical cannabis in Germany, tracked in the monthly telemedicine panel alongside the larger operators.HQGermanyRoleClinicTracked in the 42-operator panelGreenmedicaliGreenmedicalTelemedicine platform, ~533k monthly visitsDigital prescribing platform. June 2026 traffic reflects a correction period after a sharp earlier climb.HQGermanyRoleClinic~533k monthly visits (−23.6% MoM)MedCan OneStopiMedCan OneStopTelemedicine platform, ~431k monthly visitsDigital prescribing platform for medical cannabis in Germany.HQGermanyRoleClinic~431k monthly visits (−16.5% MoM)Weed.deiWeed.deMarketplace connecting patients, doctors and pharmaciesLets patients request prescriptions through partner physicians, compare pharmacy prices and live availability, and browse products. Founded by Justin Hartfield, co-founder of Weedmaps.HQGermanyRolePlatform · MarketplaceFounder: Justin Hartfield (Weedmaps)LUX99iLUX99Cologne specialist cannabis pharmacy with mail orderApotheke LUX 99 (Cannabis Apotheke®) — one of the established cannabis-focused pharmacies in Germany, offering mail-order delivery on prescription and reachable via CannGo and other platforms.HQCologne / Hürth, DERoleRetailer (pharmacy)Specialist pharmacy with mail-order deliveryGetKongiGetKongFast-growing prescribing and delivery platformDigital platform for prescribing and delivery, and the fastest climber in the June 2026 traffic panel.HQGermanyRoleClinic~393k monthly visits (+24.4% MoM — top climber)
Distribution
Where the consolidation is landing — importers, wholesalers and the EU-GMP chain.
CansativaiCansativaGermany’s largest distributor; exclusive BfArM partnerGMP- and GDP-certified B2B platform managing the full chain from import to logistics for thousands of pharmacies, and the exclusive partner of the German government for distributing domestically grown cannabis. Sole Cookies licensee in Germany.HQMörfelden-Walldorf, DEFounded2017RoleDistributorLargest distributor by share · exclusive BfArM partner$15M Series B · ~43 employeesRemexianiRemexianLargest portfolio in Germany at 203 strainsLeading German importer and distributor, majority-acquired by High Tide in September 2025. Holds the largest strain portfolio in the market and secured dual court victories against competitor Vayamed.HQGermanyRoleDistributor203 strains — the largest portfolio in GermanyParent: High Tide Inc. (Nasdaq: HITI) — 51% for ~€27.2M, Sep 2025CannamedicaliCannamedicalMajor wholesaler with 104 strainsCannamedical® Pharma (also Semdor / PS Pharma) — a leading wholesaler and distributor, and the source of the volume-weighted retail benchmark used in our pricing reconciliation.HQGermanyRoleDistributor104 strains · €5.40/g volume-weighted retail (Mar 2026)Also known as Semdor, PS PharmaFour 20 PharmaiFour 20 PharmaEU-GMP & GDP licensed; wholly owned by CuraleafPaderborn-based producer, importer and wholesaler of flower and full-spectrum extracts. Curaleaf took 55% in 2022 for €19.7M and completed the buyout of the remaining 45% in May 2026. Its ‘420 NATURAL’ brand is among the highest-selling in Germany.HQPaderborn, DEFounded2018RoleManufacturer · Distributor41 employees · ‘420 NATURAL’ among the top-selling brandsParent: Curaleaf Holdings — full ownership May 2026CantourageiCantourageManufacturer-distributor with 107 strainsGerman manufacturer and distributor holding one of the three largest strain portfolios in the market. Owns Telecan, its own online prescribing platform — a distributor moving into the demand channel.HQGermanyRoleManufacturer · Distributor107 strains in portfolioBrands: TelecanNimbus HealthiNimbus HealthFrankfurt wholesaler owned by Dr. Reddy’sFully licensed pharmaceutical wholesaler and manufacturer with 22 t of annual distribution capacity, ranking in the German top ten. Acquired by Dr. Reddy’s Laboratories in 2022 — big pharma’s entry into the German cannabis chain.HQFrankfurt, DEFounded2018RoleDistributor22 t annual distribution capacity · top-10 distributorParent: Dr. Reddy’s Laboratories (NYSE: RDY)Enua PharmaiEnua PharmaFirst institutional cannabis debt facility in EuropeGerman distributor that secured a €25M debt facility from Deutsche Bank — the signal that institutional lenders have started underwriting European cannabis.HQGermanyRoleDistributor€25M Deutsche Bank facility — a European firstalephSanaialephSanaBerlin wholesaler, importer and exporterGDP-certified pharmaceutical wholesaler sourcing certified cannabis globally, and the first to bring Australian-cultivated cannabis into the German market.HQBerlin, DEFounded2019RoleDistributorFirst to import Australian-cultivated cannabis to GermanyFounder: Boris Moshkovits · 1–10 employeesWeeco PharmaiWeeco PharmaHildesheim distributor, part of SynBiotic GroupEU-GDP certified wholesaler and importer operating under EU-GMP guidelines, with presence in Denmark, Switzerland and Greece. Supply agreement with DanCann Pharma.HQHildesheim, DEFounded2019RoleDistributorDKK 40M supply agreement with DanCann PharmaParent: SynBiotic GroupDrapaliniDrapalinMunich importer sourcing from LesothoGDP-certified importer and wholesaler founded by four childhood friends, importing from Lesotho and distributing mainly in Bavaria. Building toward vertical integration.HQMunich, DEFounded2017RoleDistributorImports from Lesotho · GDP-certifiedCanifyiCanifyDistributor, retailer and clinic operatorOperates across distribution, retail and clinic channels — one of the vertically spanning operators that makes single-category classification difficult.HQGermanyRoleDistributor · Retailer · ClinicVertically spanning operator
Pharma & devices
The finished-medicine gate, and the hardware around it.
VertanicaliVertanicalDeveloper of Exilby — the first approved cannabis painkillerMunich biopharmaceutical company specialising in cannabinoid therapies for chronic pain. Developed VER-01 (Exilby), which won German marketing authorisation in June 2026 on a three-pillar Phase III programme. Over $250M invested in R&D.HQMunich, DERoleManufacturer · R&DExilby approved Jun 2026 — 1,200+ patients across two completed Phase III trialsCEO: Dr Clemens Fischer · Lead product: Exilby (VER-01)Storz & BickeliStorz & BickelThe world’s first medical vaporiser manufacturerGerman manufacturer of medically certified vaporisers — Volcano, Mighty, Crafty, Venty — for combustion-free inhalation. Based in Tuttlingen, Germany’s medical-device hub. Owned by Canopy Growth.HQTuttlingen, DERoleManufacturer · Distributor · Retailer25+ years — first medical cannabis vaporiser maker worldwideParent: Canopy GrowthBionoricaiBionoricaPhytopharma group that founded the C3 cannabinoid divisionLeading German phytopharmaceutical company. Founded C3 Cannabinoid Compound Company, which produces pharmaceutical-grade natural and synthetic THC and CBD API in Germany; C3 was acquired by Canopy Growth in 2019. Holds several extraction and synthesis patents.HQNeumarkt, DERoleManufacturer · R&DFounded C3 — pharmaceutical-grade THC/CBD API in GermanySpinoff: C3 (Canopy Growth, 2019)
Hover or tap any operator for its company card. This is a selected view, not the full set — the complete German roster, with ownership, facilities, certifications and linked deals, lives in Decide.
Three deals, three regulatory bets.
High Tide → Remexian
~€27.2MSep 2025
Medical distribution — 51% stake
Canada’s largest retailer buys control of the German distributor holding the market’s largest strain portfolio.
Curaleaf → Four 20 Pharma
€19.7M → 100%May 2026
EU-GMP producer-distributor
Curaleaf took 55% in 2022, then bought out the remaining 45% in May 2026 — a staged move to full ownership of a Paderborn EU-GMP/GDP asset.
Organigram → Sanity Group
up to €227MFeb 2026
Platform & brands
The headline includes earnouts — roughly half of it contingent, and the highest multiple in the dataset.
Three landmark cross-border deals priced three distinct regulatory bets at 2.4×–15× EBITDA. Across the whole cycle, over €1bn in ~60 deals has flowed into German cannabis since 2017 — and roughly €450M was deployed between September 2025 and February 2026 alone.
→ In Decide company profiles and the M&A & funding tracker — every operator, deal and financing on one graph, with valuation multiples where they are disclosed.
Science
The pipeline that just rewrote the reimbursement rules.
Vertanical’s Exilby (VER-01) — the first high-THC, full-spectrum botanical ever to win pharmaceutical marketing authorisation — was approved in Germany on 9 June 2026. It got there not on one study but on a three-pillar Phase III programme, with the two completed trials enrolling more than 1,200 patients between them. Both are below, as they appear in our clinical-trials database.
Completedn = 820394 VER-01 / 426 placebo
VER-01 — placebo-controlled pivotal
Recruited Jul 2021 – Jun 2023
Registry
NCT04940741 · EudraCT 2020-000107-36
Phase
Phase III
Design
Randomised, double-blind, placebo-controlled; four phases (A: 12-week double-blind · B & C: 6-month open-label · D: randomised withdrawal)
Sites
66 sites — Germany and Austria
Population
Chronic low-back pain ± neuropathic component; mean baseline pain ~6.0 NRS; 22% neuropathic, 23.5% severe
Status
Completed (Jul 2021 – Mar 2024)
Published
Nature Medicine, Sep 2025
Primary endpoint
Met. Pain fell −1.9 NRS vs −1.4 on placebo (mean difference −0.6; p < 0.001), favouring VER-01 in every single treatment week.
- Responders (≥30% pain reduction): 54.1% vs 39.5%; rising to ~74% on long-term open-label use.
- Larger where it counts: neuropathic subgroup MD −1.5; severe-pain subgroup MD −1.0.
- No signals of abuse, dependence, tolerance or withdrawal after abrupt discontinuation.
Completedn = 384192 / 192
VER-01 vs opioids — head-to-head
Jun 2023 – Jun 2024
Registry
NCT05610813 · EudraCT 2022-001358-41
Phase
Phase III
Design
Randomised, active-controlled head-to-head against commercially available opioids; pragmatic, open-label, 1:1
Sites
41 sites — Germany, Czechia, Poland, Spain
Population
Chronic non-specific low-back pain; 61.6% female, 41.7% severe pain, 32.0% neuropathic component
Status
Completed (Jun 2023 – Jun 2024)
Published
Pain and Therapy, Sep 2025
Primary endpoint
Met. Fourfold lower risk of constipation (RR 0.25; p = 0.007); laxative use 5.8% vs 17.2% (p < 0.001).
- Superior analgesia over six months: 2.50 vs 2.16 NRS, and better sleep (2.52 vs 2.07; p = 0.009).
- Stable dosing: VER-01 held flat (~7.5 units/day) while the opioid arm escalated +18% in morphine-equivalents.
- Tolerability trade-off: similar overall TEAEs (73.0% vs 73.7%) but different profiles — VER-01 dizziness 22.2%; opioids constipation 23.1%. No deaths.
Pillar 3 — active, not yet reported
VER-01 in radicular chronic low-back pain
The single largest active Phase III trial in the Cannamonitor clinical-trials database, designed to align with the US pivotal programme.
n = 810NCT06956014Registered — start Sep 2026, completion Nov 2027
The indication gap
~76%
of German patients report broad chronic pain — not the narrow indication Exilby is authorised for.
That is the hole in the reform. From 1 January 2027 extracts are gated behind a six-month trial of an “approved finished medicine” — but for most patients, that alternative does not yet exist. Source: BfArM Begleiterhebung (76.4% chronic pain).
The database behind these cards
1,305 trials
Tracked across 11 registries, of which 483 are active. Every card carries registry ID, phase, design, sites, enrolment, population, primary endpoint and publication — the same fields, for every trial.
→ In Decide the clinical-trials pipeline and the Exilby datapack — trials, endpoints and approvals, tracked to source.
The data behind this page
This page is a summary. Decide is the source.
Everything above is one market, drawn from seven data layers. In Decide, those same layers cover 120+ markets — and they cross-link, so a company links to its deals, its earnings, its country and the news that moves it. Click any layer to see inside it.
Every layer cross-links — a company links to its deals, its earnings, its country and the news that moves it. Choose a layer below to see inside it.
Layer 01 · Germany profile
Countries
Every market on one page — value, patients, imports, sources and every linked asset, so the country view is the entry point to everything else.
Countries › Germany
205 t
Imports 2025
€1bn+
Pharmacy market
~900k
Patients
−52%
Retail flower
| Linked asset | Type | Updated |
|---|---|---|
| Import, export & production | Market dataset | Quarterly |
| Patient & reimbursement | Market dataset | Quarterly |
| Telemedicine traffic panel | Market dataset | Monthly |
| German operators | Companies | Live |
| GKV reform deep-dive | Insight | Jul 2026 |
One page per market. 120+ countries, the same schema in each.
Layer 02 · 6 live German series
Market datasets
Six German datasets kept on the source cadence: imports / exports / production, patient / prescriber / reimbursement, prevalence & demand sizing, telemedicine traffic, cross-country telemedicine, and clubs & lounges.
Market datasets › Germany imports
Imports, quarterly (t)
Q124
Q224
Q324
Q424
Q125
Q225
Q325
Q425
Q126
9
quarters on record
BfArM
primary source
Quarterly
refresh cadence
kg
stored unit
| Series | Latest | Cadence |
|---|---|---|
| Total imports | 50.5 t (Q1 26) | Quarterly |
| By country of origin | 8 origins | Quarterly |
| Exports | 5.9 t (2025) | Quarterly |
| Domestic production | 2.36 t (2025) | Annual |
Six live German datasets. Exportable series, not screenshots.
Layer 03 · German operators
Companies
Producers, platforms, distributors and pharma — profiled and cross-linked to their deals, earnings, facilities and the news that moves them.
Companies › operator profile
Remexian
Distributor · Germany
203 strains — the largest portfolio in Germany.
Parent: High TideEU-GDP
| Linked record | Value |
|---|---|
| Acquisition (Sep 2025) | ~€27.2M |
| Parent earnings | 🔒 |
| Strain portfolio | 203 |
| Court rulings | 2 wins |
Every operator profiled and linked to its deals, earnings, country and news.
Layer 04 · M&A · earnings · trials
Trackers
Three filtered views of one graph: M&A and funding, earnings and financials, and science and clinical trials.
Trackers › M&A & funding
| Date | Parties | Value | Type | Multiple |
|---|---|---|---|---|
| Feb 2026 | Organigram → Sanity Group | €227M | Platform | 🔒 In Decide |
| May 2026 | Curaleaf → Four 20 Pharma | €19.7M | Distribution | 🔒 In Decide |
| Sep 2025 | High Tide → Remexian | €27.2M | Distribution | 🔒 In Decide |
| Dec 2025 | Cronos → CanAdelaar | €58M | Production | 🔒 In Decide |
~60 German deals since 2017. Same graph, filtered three ways.
Layer 05 · German sources, translated
News & Regulatory
Krautinvest, Business of Cannabis, Weed.de, Deutsche Apotheker Zeitung and Pharmazeutische Zeitung — tracked, translated and filterable.
News & Regulatory › Germany
Country: GermanyTheme: ReimbursementCompany: any
DEBundestag votes to strike flower from GKV reimbursementKrautinvest · 10 Jul 2026 · translated
DESix-month finished-medicine gate confirmed for extractsPharmazeutische Zeitung · 11 Jul 2026 · translated
DEMedCanG amendment targets telemedicine consultationsDAZ · Jun 2026 · translated
DEExilby wins German marketing authorisationBusiness of Cannabis · 9 Jun 2026 · translated
German-language sources tracked and translated, filterable by country, company and theme.
Layer 06 · 15+ German datapacks
Insights
The analyst library: the GKV reform, demand sizing, EKOCAN pricing, the pricing brief and the 2025 data brief — analysis with the working shown.
Insights › the German library
DATAPACK
Germany pricing 2023–26
Contents
1The reconciled retail line, €9.65 → €4.65/g
2GACP and EU-GMP wholesale bands by THC tier
3The Canada customs corridor cross-check
4What the certification premium is worth
15+ German datapacks. Analysis with the working shown.
Layer 07 · Germany’s month
The Monthly Brief
The recap layer that sits on top of all of the above: what changed, ranked by consequence.
The Monthly Brief › Germany, July 2026
1The reimbursement cut landsFlower out of §31(6) SGB V since 30 Jul, no transition.
2Imports post their first declineQ1 2026 −16.8% QoQ — maturation, not collapse.
3Curaleaf completes Four 20 PharmaFull ownership of a Paderborn EU-GMP asset.
Every month, hierarchised by consequence. Archive back to 2024.
How we build it
Why these numbers hold up.
We don’t estimate the German market. We compile it from primary records, then cross-validate each layer against the others — and correct it in public when a cleaner measure exists.
1Primary sources
Official records first — BfArM (imports), GKV-Gamsi (reimbursement) and Statistics Canada (customs). Where no official series exists — telemedicine traffic and wholesale pricing — the numbers are Cannamonitor’s own compilation from primary sources. Compiled, not modelled.
2Cross-validation
Each layer is checked against the others. Retail is reconciled against wholesale and the customs corridor — Canada’s declared price of CA$2,877/kg ≈ €1.9/g lands between the GACP and EU-GMP bands. Import totals are reconciled against pharmacy sell-through (70–75% in 2025).
3We correct our own record
Germany’s 2025 imports were widely reported as 201.1 t. After the INCB quota was raised in October 2025, the final quarterly sum came in at 205.2 t — and that is the figure used on this page. Decision-grade means showing the working, and restating it when a cleaner measure exists.
4Honest limits, on the source cadence
Compiled traffic estimates carry ±10–15% uncertainty on smaller sites; GKV covers only ~20% of pharmacy sales; the domestic-production figure is an INCB pre-estimate. Quarterly refresh for BfArM and GKV (~6–8 week lag), monthly for traffic.
205 t
imports, 2025
€1bn+
pharmacy market
~900k
patients
Primary
BfArM · GKV · customs
120+
markets in Decide
Sources: BfArM quarterly import/export releases (~6–8 week lag) · GKV-Gamsi statutory reimbursement · Statistics Canada customs (HS 1211.90.10) · BfArM Begleiterhebung (indication split) · INCB (domestic production pre-estimate) · Cannamonitor compilation for telemedicine traffic and wholesale pricing · Cannamonitor Clinical Trials database (1,305 trials, 11 registries) · Cannamonitor Germany Operator Map (28 companies).
Free — the Germany pricing brief
Get the German pricing brief — free.
The full retail and wholesale pricing breakdown, packaged as one downloadable datapack. Yours free, for a work email.
What’s inside
- The reconciled retail line — €9.65 → €4.65/g, April 2024 to June 2026.
- The sub-€2/g wholesale bands — GACP €0.60–2.50/g and EU-GMP €1.25–3.48/g, by THC tier.
- The Canada customs cross-check — CA$2,877/kg ≈ €1.9/g, and what the certification premium is really worth.
Germany: retail and wholesale pricing, 2023–2026.
PDF datapack · sourced throughout.
PDF datapack · sourced throughout.
Loading the form…
The brief is a snapshot. The same pricing — refreshed monthly and cross-validated against customs — is a live layer in Decide. Start now →
Objections
Common questions.
A ~€1bn+ pharmacy sell-out in 2025, 205 t imported and ~900k patients — the largest regulated medical cannabis market in the world.
Q1 2026 posted the first import decline on record (−16.8% QoQ, 60.8 t → 50.5 t). Growth is maturing, and the July 2026 reimbursement cut adds downside. Both are tracked live in Decide.
Official sources — BfArM for imports, GKV-Gamsi for reimbursement and Statistics Canada for the customs corridor — plus Cannamonitor’s own compilation from primary sources for telemedicine traffic and wholesale pricing, all cross-validated against each other.
201.1 t was the headline before Germany’s INCB quota was raised in October 2025. The final quarterly sum for 2025 is 205.2 t, and that is the figure used here.
It lands in two provisions. Flower was struck from §31(6) SGB V on 30 July 2026 — already in force, with no transition period, applying even to ongoing therapies. From 1 January 2027 standardised extracts, dronabinol and nabilone stay reimbursable only after a six-month trial of an approved finished medicine. Together that is ~82% of the €249M reimbursed market.
Yes — 14 German master stories across nine subjects, each scored for momentum and risk and linked to the regulators, laws and licences behind it. Reimbursement is the most negative on the board at −90; home cultivation is the most positive at +80.
The full German series, cross-country comparators, the German company profiles, the M&A / earnings / clinical-trials trackers and the regulatory tracker — for 120+ markets.